Last Chance! Homes are a Bargain Compared to Historic Norms

A loaf of bread used to be a nickel. A movie ticket was a dime. Not anymore. Houses were also much less expensive than they are now. Inflation raised the price of all three of those items, along with the price of almost every other item we purchase.
The reason we can still afford to consume is that our wages have also risen over time. The better measure of whether an item is more expensive than it was before is what percentage of our income it takes to purchase that item today compared to earlier. Let’s look at purchasing a home.
The COST of a home is determined by three major components: price, mortgage interest rate, and wages. The big question? Are we paying a greater percentage of our income toward our monthly mortgage payment today than previous generations? Surprisingly, the answer is no.
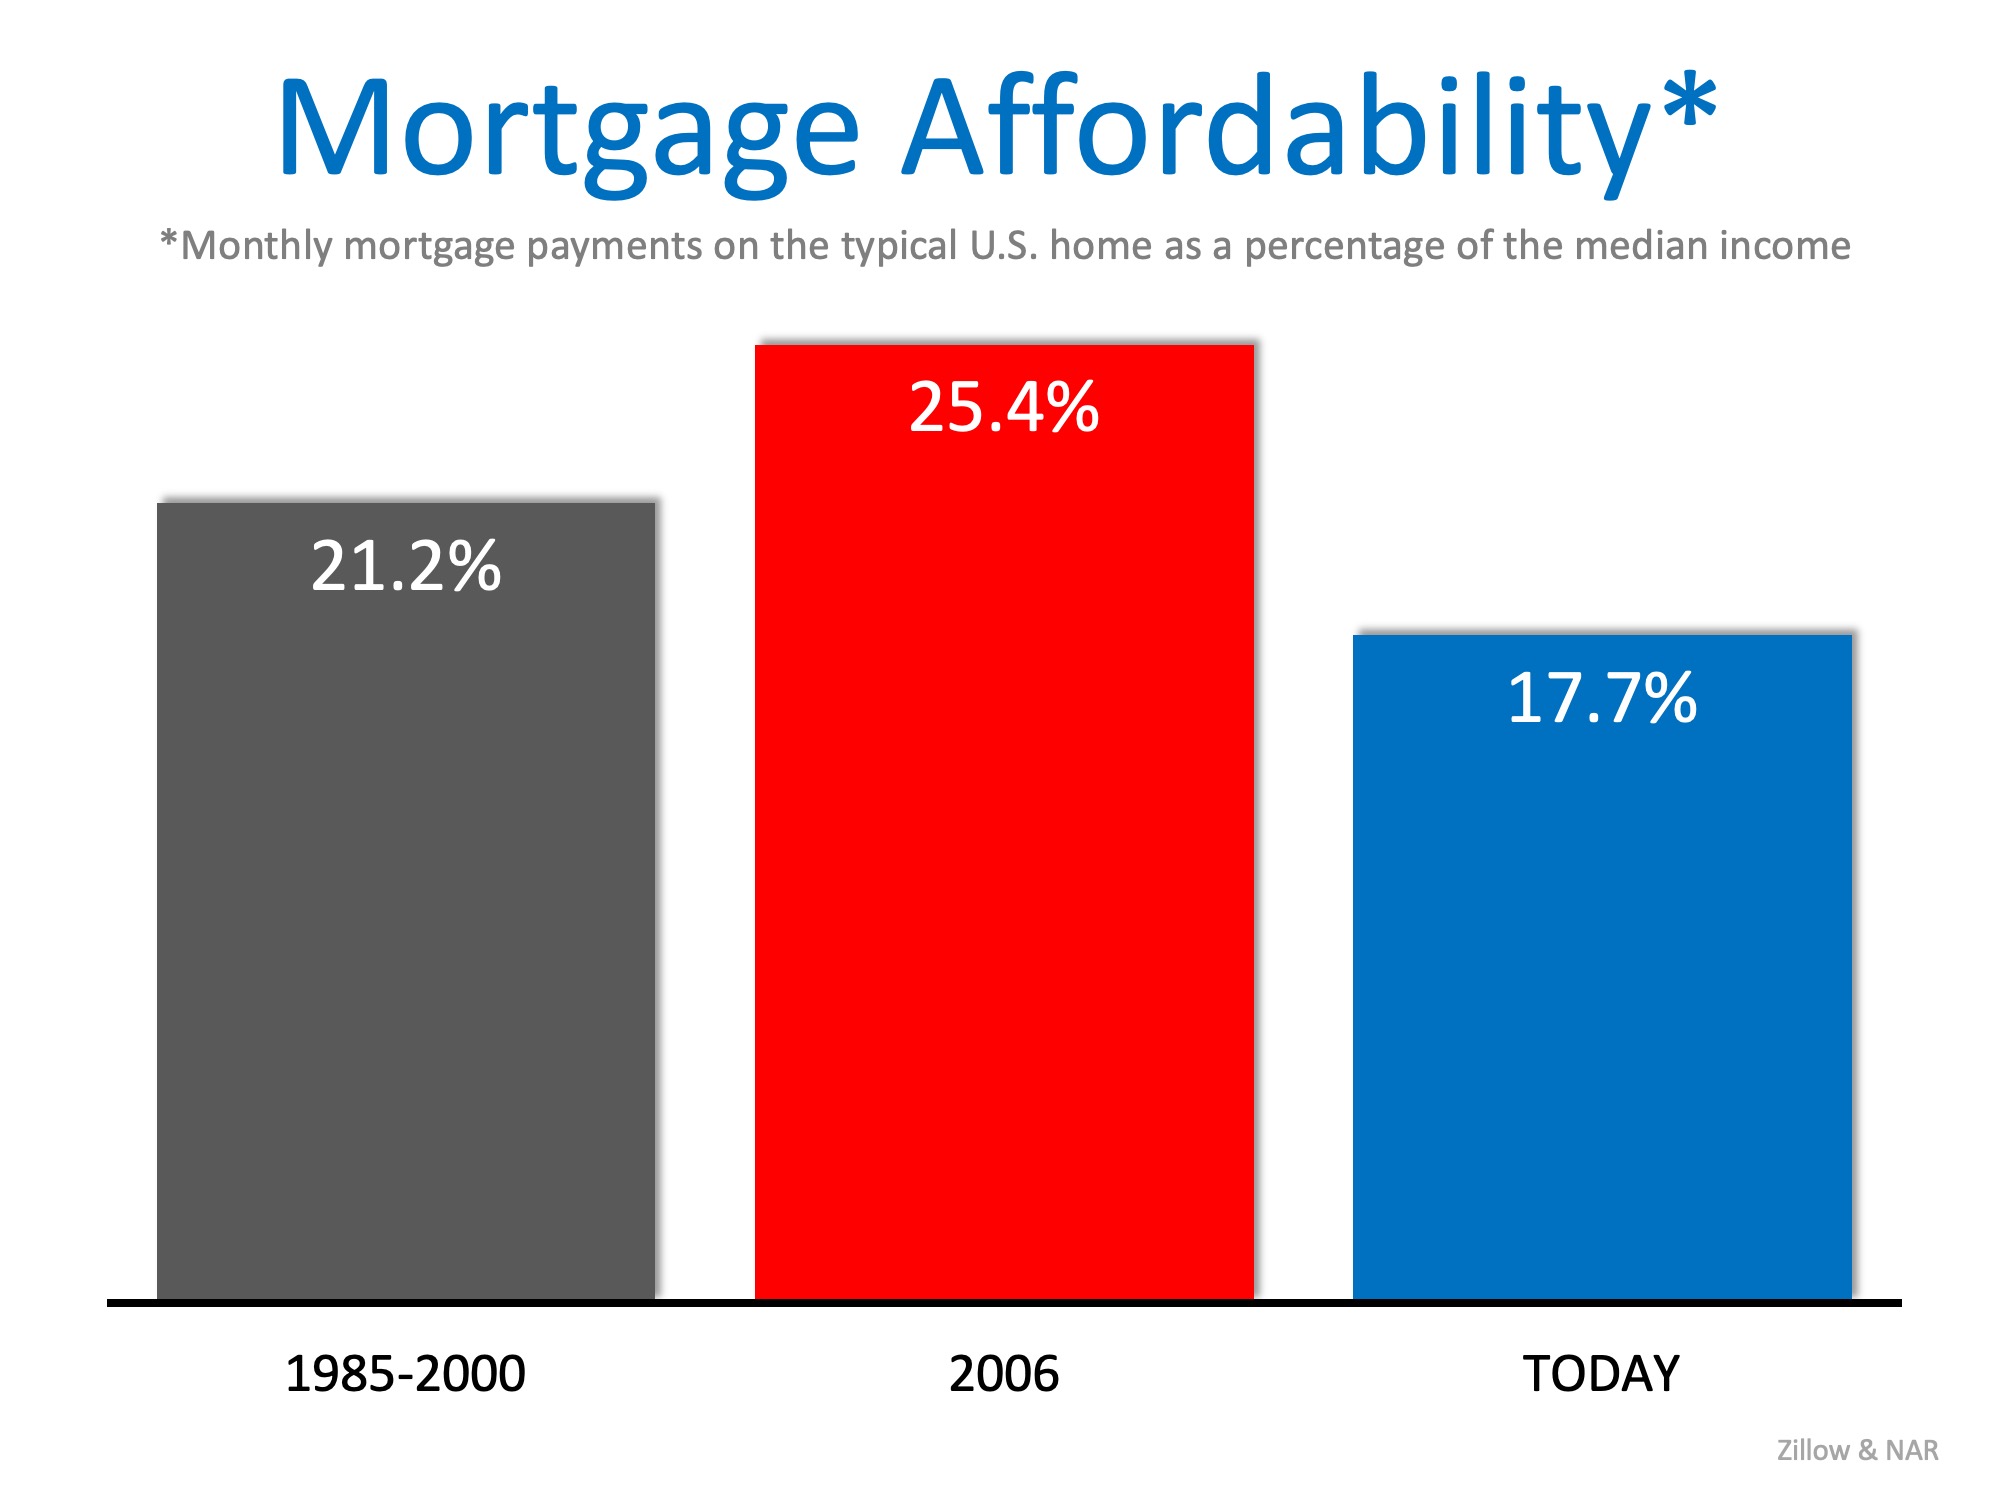
Historically, Americans have paid just over 21% of their income toward their monthly mortgage payment.
Though home prices are higher than before, wages have risen as well. And, the most important component in the cost equation – the mortgage rate – is dramatically lower than it was in the 1970s, 1980s, 1990s, and 2000s.
Today, according to the latest Home Affordability Index just released by the National Association of Realtors, Americans are paying 17.4% of their income toward their mortgage payment. That is much lower than the 21% average previous generations have paid.
Bottom Line
The cost of purchasing a home today is a bargain compared to previous generations when we look at it from a percentage of income basis. However, with mortgage rates expected to increase and home prices continuing to appreciate, that will not always be the case. Whether you are buying your first home or looking to move-up to a more expensive home, purchasing sooner rather than later probably makes sense.
To view original article, view Keeping Current Matters.
Selling This Fall? You Want To Get These 4 Things Right.
Selling your house this fall is absolutely doable. Buyer activity typically starts to slow while the number of homes for sale climb – and you need the right strategy to get attention in this type of market.
Selling This Fall? You Haven’t Missed Your Window
Getting your house sold this season comes down to how well it’s priced and presented, and that’s where a local agent shines.
Thinking About Tapping into Your 401(k) To Buy a Home? Read This First.
No matter which route you take, talk with a financial expert first. The buyers who come out ahead build a solid plan with the right professionals before starting their journey to homeownership.
Most Home Sales Close – Here’s How To Keep Yours on Track
Some reasons are outside a seller’s control, like whether a buyer’s loan clears or whether they sell their own home in time. But there are a few proactive things you can do to help make sure your sale goes as smoothly as possible.
Selling a Luxury House? Here’s Why Now Is a Good Time
High-end buyers tend to feel less of the affordability pressure weighing on many households today, so they keep buying even when the wider market slows.
More Homes, Better Prices: A Buyer’s Summer
Sellers are reading market conditions and are pricing accordingly from the start rather than listing high and cutting later, and buyers are taking note and making bids.